
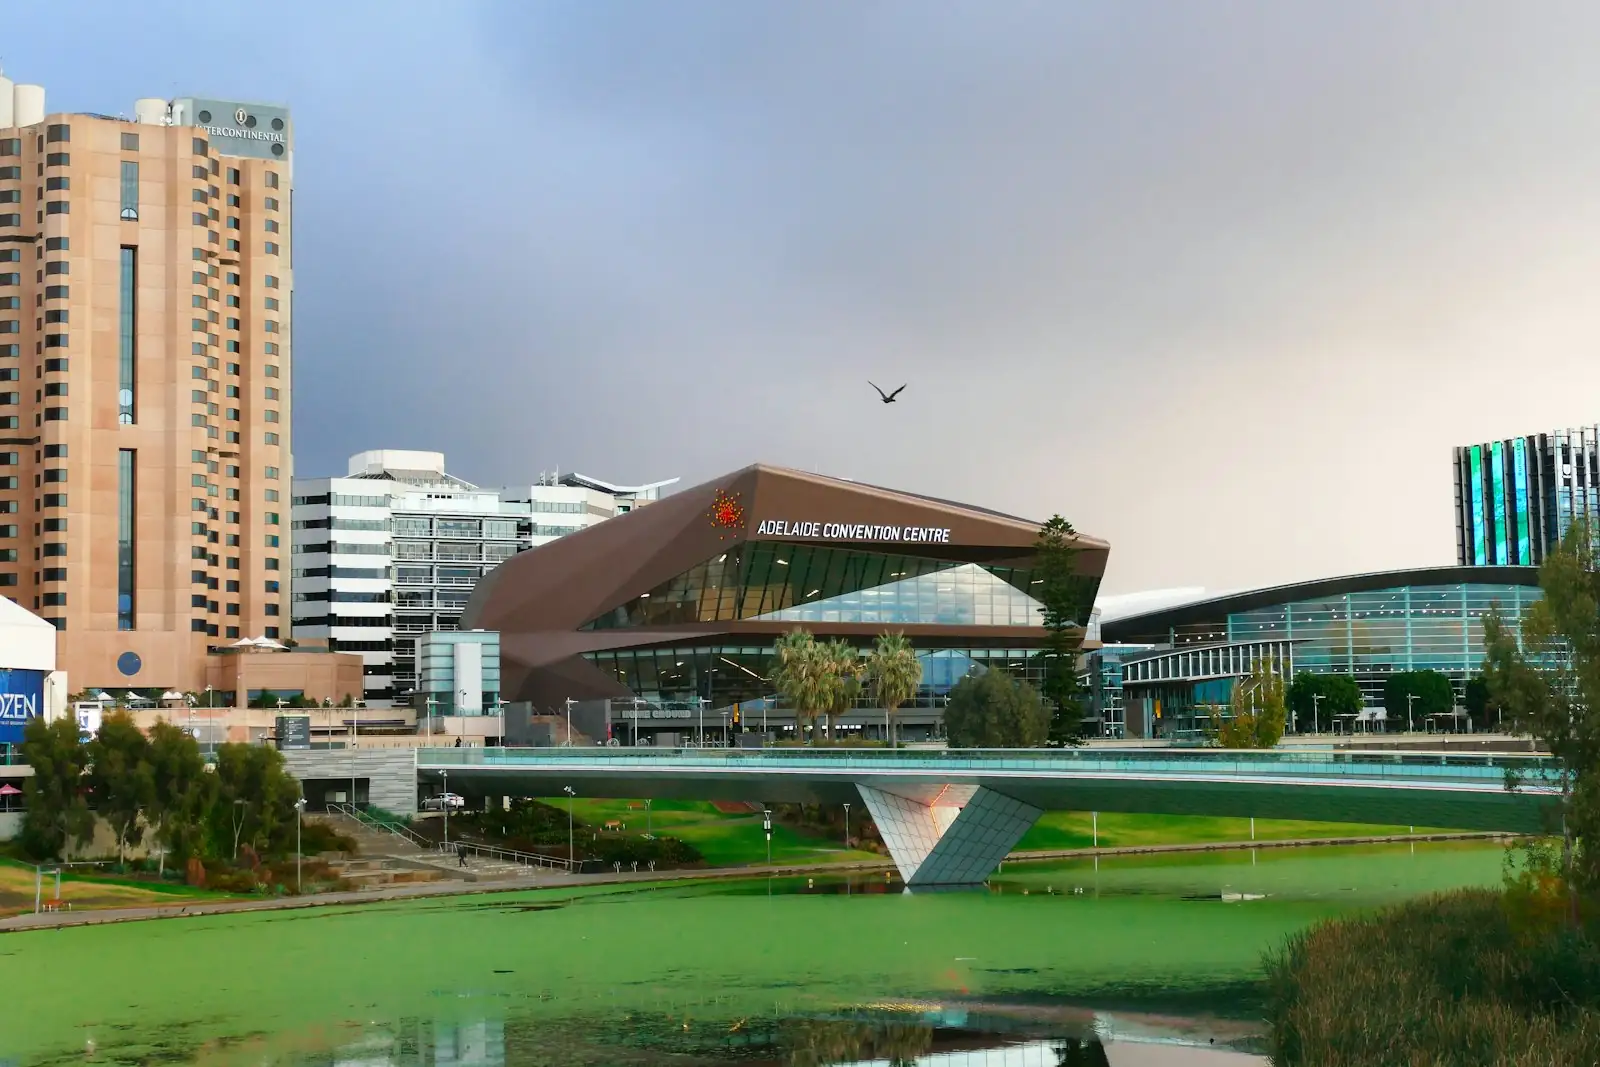
Short answer: Caveat loans in Adelaide are lodged with Land Services SA and can be funded in as little as 24 hours. Instant Business Finance lends $20,000 to $5 million against South Australian property with no financials required and bad credit considered.
How a caveat works on a South Australian title
In South Australia the caveat is lodged with Land Services SA. Lodgement is electronic and quick, and no consent is required from your existing mortgage lender, so an Adelaide file can be funded within 24 hours of the first enquiry.
Your existing home loan is untouched throughout. The caveat is withdrawn from the title when the loan is repaid.
Why the Adelaide market rewards speed differently
Adelaide is a smaller market with a high proportion of long-established family businesses — manufacturing, food and wine, defence supply chain, professional services. Many of them own their premises outright or close to it.
That produces a specific situation we see often: a business with real property equity, a long trading history and a bank that still says no, because the bank is assessing serviceability from figures that reflect a hard year rather than the underlying position. A caveat loan looks at the equity and the exit instead, which is why the answer is frequently different.
There is a second pattern specific to Adelaide: succession. A founder steps back, the next generation takes over, and the bank reassesses the business as though it were new despite forty years of trading behind it. The property is still there and so is the trading history, but the application is treated as a fresh one.
What Adelaide owners use caveat loans for
| Situation | Why a caveat suits it |
|---|---|
| ATO debt | Cleared without refinancing a long-held mortgage |
| Equipment for a manufacturing contract | Funded against equity rather than the order |
| Seasonal gaps in food and wine | Bridges a known cycle with a defined exit |
| Buying commercial premises or a business | Moves faster than a bank commercial application |
| Consolidating business debts | One facility, one exit, structured around the sale or refinance |
Across Adelaide and regional South Australia
We lend against property across metropolitan Adelaide and regional South Australia.
- Adelaide CBD and inner suburbs
- Northern suburbs and Elizabeth
- Southern suburbs and Noarlunga
- Eastern suburbs and the Adelaide Hills
- Barossa, Riverland, Mount Gambier and regional SA
What works as security in South Australia
Metropolitan Adelaide residential and commercial property is standard security, and South Australian files often have an advantage: a high proportion of long-held property with little or no debt behind it.
Owner-occupied commercial and industrial premises in the northern and western industrial areas are common, particularly among manufacturing and defence supply businesses that bought their premises decades ago. Those files frequently have the cleanest equity position we see anywhere.
Rural and viticultural property in the Barossa, Riverland and the south-east is accepted and is assessed on its own terms. Land whose value rests substantially on a crop, a licence or a water entitlement takes more work to value and will generally need a full valuation rather than a desktop one.
Property held in a family trust is very common in South Australia and is not an obstacle. It does mean every trustee needs to be available to sign, which is worth confirming before the file starts rather than on the day.
An Adelaide file, start to finish
A family manufacturing business in the northern suburbs, trading for over thirty years, had an ATO debt built up through one difficult year and a payment plan that had defaulted. The bank declined on serviceability.
The premises were owned outright by the family trust. The equity position was unambiguous, and the exit was a refinance already in progress with a commercial lender that needed the tax debt cleared before it could settle. The caveat was lodged with Land Services SA and the ATO was paid within 24 hours.
The refinance settled seven weeks later and the caveat was withdrawn. The bank that declined the original application was the same bank that later wrote the long-term facility.
The full step-by-step is on the caveat loan process page.
Frequently asked questions
We have owned our premises for decades. Does that help?
Considerably. A long-held property with little debt behind it gives the cleanest equity position there is, which generally means both a faster answer and a sharper rate.
Can vineyard or rural property be used as security?
Yes, and it is assessed on its own terms. Where value rests substantially on a crop, a licence or a water entitlement, expect a full valuation rather than a desktop one.
How fast can I get a caveat loan in Adelaide?
As little as 24 hours. Lodgement with Land Services SA is electronic; the time is spent confirming ownership, equity and your exit.
Do you lend in regional South Australia?
Yes, including the Barossa, Riverland and Mount Gambier. Rural and specialised property may need a full valuation.
My business has traded for 30 years but the bank said no. Can you help?
Often, yes. A caveat loan is assessed on the equity in the property and how the loan will be repaid, not on serviceability from your last set of figures.
Can I use commercial premises as security?
Yes. Commercial and industrial property, investment property and vacant land all work.
Does it cost anything to apply?
No. There's no cost to apply or check your eligibility. All costs are set out in writing in your loan offer before you sign anything.
Will checking my eligibility affect my credit score?
No. Our 60-second eligibility check doesn't make a credit enquiry. A credit check is only done later, with your consent, if you decide to proceed.
