
On the land, timing is set by the season, not the bank. When the header needs replacing or inputs are due before harvest, you need an answer this week. We lend against rural property and understand seasonal income.
What farming & agriculture use fast finance for
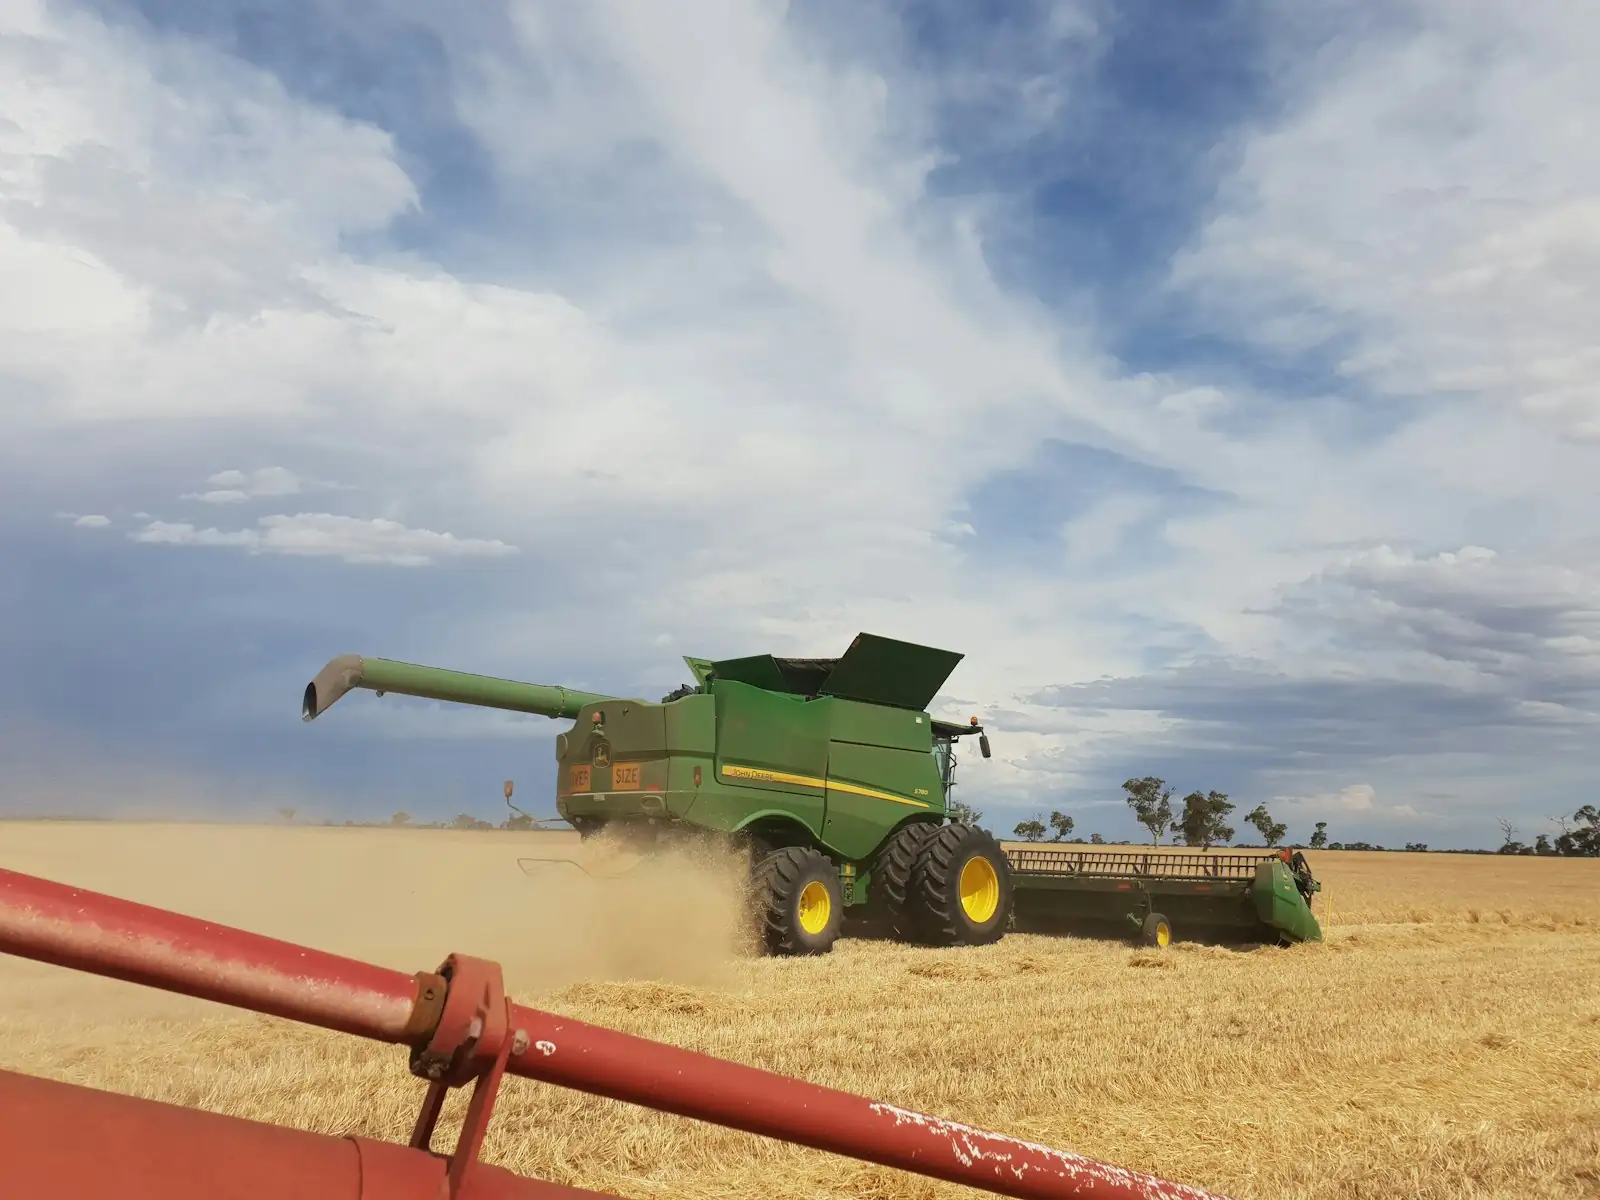 Buy equipment or machineryNo property needed
 Smooth seasonal cash flowNo property needed
 Recover from flood, fire or stormWith or without property
 Buy vehicles, utes & trucksNo property needed
 Pay an ATO or tax debtWith or without property
 Consolidate business debtsWith or without property
Best-fit loan types
A farm year is one long cash-flow gap
Almost every other business converts input into revenue within weeks. A farm converts it across a season, and sometimes across a year. Seed, fertiliser, fuel, agronomy and labour are spent months before anything is sold, and the price at the far end is set by a market nobody in the paddock controls.
That alone would be manageable if the timing were reliable. It is not. A late break, a wet harvest, a heat event at flowering or a shipping delay at the port moves the income date without moving any of the cost dates. The business is sound; the calendar simply does not cooperate.
Which is why farm finance is unusual: the security is often excellent and the serviceability test is almost meaningless. A property carrying substantial equity against a year of figures distorted by drought or a bumper season tells a bank very little, and tells a lender assessing equity and exit almost everything it needs.
What farms and ag businesses borrow for
| The need | When it lands | Usual answer |
|---|---|---|
| Inputs for the season | Spent before anything is sold | Short-term funding repaid at harvest or sale |
| Machinery breakdown mid-harvest | The most expensive possible week for it to happen | Same-day funding against property |
| Buying adjoining land | Neighbouring country comes up once in a generation | Bridging against existing land, refinanced later |
| Livestock purchase | Buy the weaners before the sale money arrives | Short-term funding repaid by turn-off |
| Drought or flood recovery | Costs land immediately, assistance and insurance do not | Property-secured funding |
| ATO debt after a good year | Tax assessed on a year the current season does not resemble | Property-secured funding, no financials |
How is rural property assessed as security?
Case by case, and more conservatively than metropolitan property, for one honest reason: the market for any given rural holding is narrower, so it takes longer to sell if it ever came to that. That affects the amount available and sometimes the speed, not whether the loan can be done.
Distance matters more than most owners expect. A property near a regional centre with an active market is assessed much like a suburban one, often from a desk. A holding further out generally needs a physical valuation, which adds days rather than hours. If a deadline is tight and you have a choice of security — a town house, a shed block, a property closer in — the closer one is the faster route.
Water entitlements, leases, share-farming arrangements and country held across several titles are all ordinary and all worth mentioning at the start rather than being discovered mid-assessment. So is anything unusual already registered on the title, which is common on land held in the same family for decades.
Do you lend to ag contractors and not just landholders?
Yes. Harvest contractors, spray operators, shearing contractors, earthmoving and fencing businesses are funded the same way as any other trading business: on property equity and a clear exit where property is available, and on trading records through cash-flow lending where it is not.
Contractors have the sharpest version of the timing problem, because they fund fuel, wages and machinery across a season and invoice clients who are themselves waiting on a harvest cheque. A delay upstream arrives twice: once as a late payment and once as a client who wants next season on terms.
The practical structure is usually short-term funding written against property with a term matched to when the season’s invoices actually settle rather than when they are issued. Build a margin into that term. A wet harvest that pushes everything four weeks is an ordinary event, and a loan written without room for it turns a weather problem into a finance problem.
Two fast lanes
- Check eligibility60 seconds online, with no credit score impact.
- We pick your fastest laneProperty-secured (up to $5M, no financials) or cash-flow (bank statements).
- Get a decisionUsually the same business day, with every cost in writing.
- Get fundedIn as little as 2 hours (cash-flow) or 24 hours (property-secured).
Frequently asked questions
Do you lend against rural property?
Yes. Rural and farming land can be used as security, subject to location and value.
Can repayments be timed to harvest?
With property-secured loans, interest can often be capitalised and repaid from harvest proceeds.
Does it cost anything to apply?
No. There's no cost to apply or check your eligibility. All costs are set out in writing in your loan offer before you sign anything.
Will checking my eligibility affect my credit score?
No. Our 60-second eligibility check doesn't make a credit enquiry. A credit check is only done later, with your consent, if you decide to proceed.
